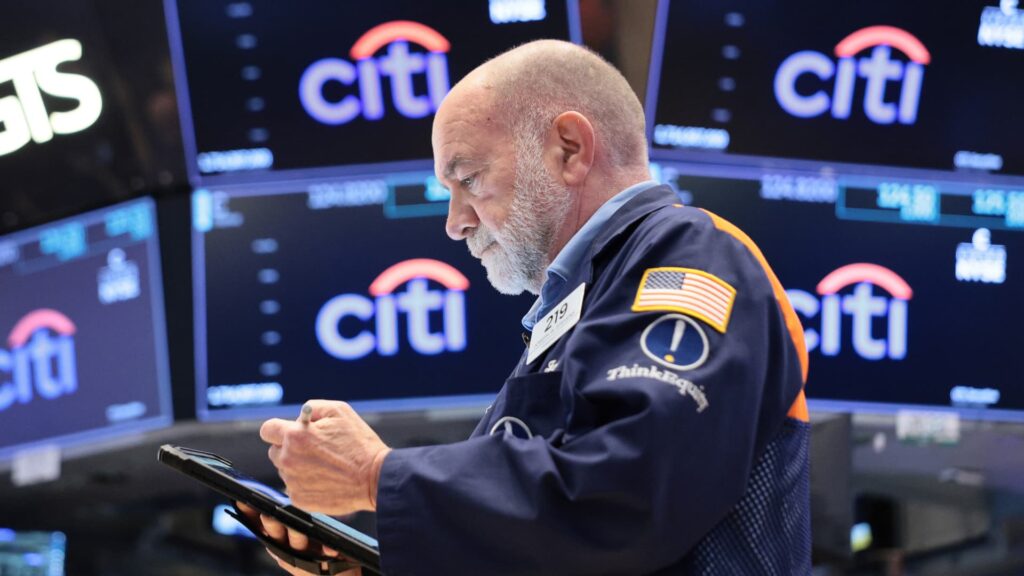
Citi Wealth would have welcomed a deeper stock-market correction this year, seeing any bigger pullback as an opportunity to buy as strong corporate earnings continue to underpin equities. “We wouldn’t have minded a little bit more of a correction,” said Jeanne Sun, head of portfolio advisory at Citi Wealth, told CNBC’s “Squawk Box Asia” on Thursday. “Because the fundamentals are so strong, earnings growth is so resilient; it is actually a good opportunity to buy.” Citi Wealth caters to clients across the wealth spectrum, ranging from ultra-high-net-worth individuals and family offices to mass-affluent investors and professionals. The wealth management arm manages over $1 trillion in client balances globally. “We were hoping for more of that, and what we’ve seen all year is that pullbacks and corrections have been amazingly shallow,” she added. Citi Wealth maintains a bias toward equities heading into the fourth quarter, even as higher interest rates and elevated Treasury yields have raised questions over how long stocks can withstand rising borrowing costs. Sun said the rise in interest rates has been driven more by real rates than inflation expectations, which she sees as reflecting the underlying strength of the U.S. economy. “Equities is still the place to be because earnings have been fundamentally strong,” she said. The portfolio advisory head expects a “pretty good fourth quarter in aggregate,” though she cautioned that volatility could persist into October amid uncertainty surrounding monetary policy and the U.S. midterm elections. Earnings resilience Sun said higher borrowing costs have so far failed to overwhelm the benefits companies are getting from robust economic and earnings growth. “If you’ve got rising rates but also very strong growth, those two might net each other out,” she said. “What we’re actually seeing in the actual earnings reports is that growth is actually still doing much better in overcoming any of the increase in rates.” That also means there isn’t necessarily a particular level of Treasury yields that would automatically derail the stock market, according to Sun. Instead, investors should watch for evidence that higher rates are beginning to weaken demand and corporate profits. For now, Citi isn’t seeing those signs. Consumer spending has remained relatively resilient despite weak sentiment, while corporate capital expenditure remains strong, Sun said. Even mortgage rates above 7% haven’t caused the kind of economic slowdown that might historically have been expected from sharply higher borrowing costs. Sun pointed to constrained housing supply as one reason the relationship between rates, housing activity and the broader economy may be different this time. The outlook isn’t without risks. Investors are already heavily positioned in many of the strongest companies, while expectations for corporate earnings have continued to rise. That creates a higher bar for companies to clear and could contribute to near-term volatility even when earnings remain fundamentally strong. “Our expectation is that earnings are going to continue to be that gift,” Sun said. But with investors continually wanting more, she added, the question following earnings beats increasingly becomes: “is it enough?”